
28 August 2026
Could drought damage your home insurance claim?
2 minutes
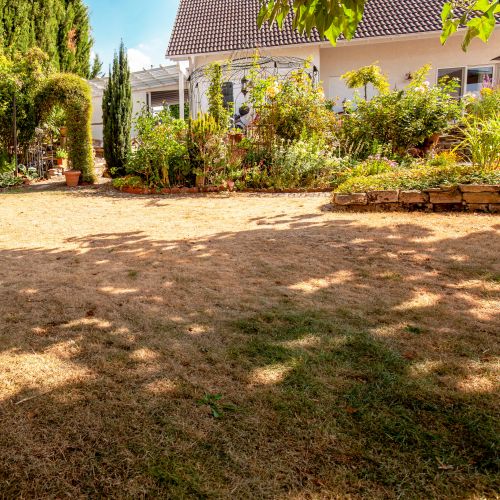
Prolonged heat can bring risks many homeowners never consider until it's too late. From wildfires to subsidence, here's what drought could mean for your home and insurance policy.
Key takeaways
Drought can increase the risk of wildfires, flash flooding and subsidence. Very dry ground struggles to absorb heavy rainfall, making sudden flooding more likely.
Subsidence is one of the biggest long-term risks, particularly in areas with clay-rich soil.
Reviewing your policy now could help avoid unexpected surprises later.
England has recorded its driest July since records began in 1836, with more than 70% of the country declared in drought at one point. Large parts of Wales were also affected, with the UK endured five heatwaves. While many of us enjoy warm weather, prolonged periods of heat and low rainfall can create problems that stretch far beyond a brown lawn. Wildfires, flash flooding and subsidence can all become more likely during and after drought conditions. So, what does that mean for homeowners?
Do home insurers cover wildfires?
Most buildings insurance policies cover fire damage, including damage caused by wildfires. However, the level of cover and any policy conditions will vary between insurers, so it's important to check your wording carefully.
There are also practical steps you can take to reduce risk:
Clear gutters and roof spaces of dry leaves and debris.
Move log piles, compost heaps and garden waste away from buildings.
Keep grass trimmed, particularly if your property borders open land.
Repair damaged roof tiles and other vulnerable areas.
If you own a thatched property, be especially careful. Many insurers include specific requirements around barbecues, fire pits and other naked flames. Following these conditions helps reduce risk and can help ensure your cover remains valid.
Why a heatwave can mean high flood risks
It sounds backwards, but drought can actually increase the chances of flooding. When the ground becomes extremely dry, it hardens and struggles to absorb water. If heavy rain arrives suddenly, water is more likely to run across the surface rather than soaking into the soil. The result can mean flash flooding.
This can affect areas that may never have considered themselves at risk before. Surface water flooding can develop quickly, causing damage to homes, gardens and possessions. That's why it's worth prepping for the worst and reviewing your insurance cover before the weather changes, not after.
Subsidence: the biggest long-term threat?
Subsidence occurs when the ground beneath a property moves, causing foundations to shift. It's particularly common in areas with clay-rich soil, which shrinks as it dries out during long periods of hot weather.
Recent industry figures show insurers paid out £72 million in domestic subsidence claims during the second quarter of 2026 alone, while the average claim reached a record £20,000. Common warning signs include:
Cracks appearing suddenly in walls.
Diagonal cracks that are wider at the top than the bottom.
Cracks wider than 3mm.
Doors or windows becoming difficult to open.
Wallpaper wrinkling, ripping or pulling away from walls.
Trees, large shrubs and leaking drains can also contribute to the problem by affecting moisture levels in the ground. If you notice signs of subsidence, contact your insurer before arranging repairs, as they may want to assess the damage first.
Review your cover before the weather changes
Extreme weather is already increasing claims costs. Between April and June 2026, the average home insurance payout exceeded £7,000 for the first time. The average weather-related claim from flooding, storms and burst pipes rose to £8,548. As severe weather events become more frequent, the cost of repairing homes is also rising. That doesn't automatically mean every homeowner will see significant premium increases, but it does underline the importance of having the right cover in place.
The good news? Small preventative measures can make a difference. Maintaining drains, managing nearby trees, repairing leaks promptly and spotting early signs of damage can all help reduce future problems. And whether it's wildfire damage, flash flooding or subsidence, understanding what your policy covers is the best way to avoid nasty surprises.
If you're unsure whether your home insurance is keeping pace with changing weather risks, speak to your local Howden team for a review of your cover and peace of mind for the months ahead.
Related Products
Trust Howden, a home insurance broker, to help you find a tailor-made home policy that meets your budgetary and insurance expectations.
Have a problem in your home that needs fixing immediately? Look no further than a home emergency insurance policy to keep your home protected at all times.
If your home insurance policy doesn’t quite do enough to comprehensively protect your solar panels, turn to our flexible solar panel insurance.
Be ready for instability beneath your home with subsidence insurance you can bank on.